
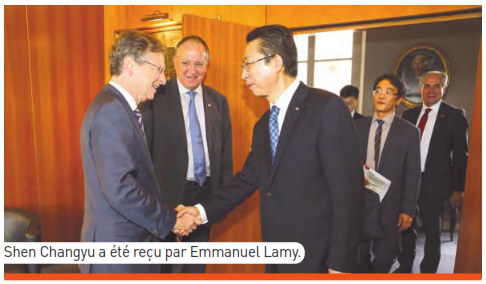
Saint-Germain-en-Laye as the EPO's clandestine 'branch'? Battistelli and Lamy with Commissioner Shen of the Chinese State Intellectual Property Office and Raimund Lutz lurking in the background.
"What would that make stakeholders think (if they all knew about it)?"What will António Campinos, a former banker (at a notorious Portuguese bank), do about all this? He can't quite defy Battistelli's will, can he? He knows where his job came from and they've long been close. Will he carry on gambling with stakeholders' money? What would that make stakeholders think (if they all knew about it)?
Well, the main stakeholder in all this is EPO staff, e.g. their pensions. And SUEPO has just written about this as follows:
22 June 2018
The new EPO Treasury Investment Fund – institutionalized gambling with someone else’s1 money?
Dear colleagues,
Through a combination of reduced career progression and extraordinary productivity gains, the Office has made an operating surplus of the order of several hundred million Euros each year as well as paid for in full for its new building in The Hague. Yet the Office’s cash reserve today still amounts to around €2.4 billion.
It was foreseen by a decision2 of the Administrative Council (AC) that any such surplus generated by staff’s work was to be transferred into the Reserve Fund for Pensions and Social Security (RFPSS) to cover future obligations. The RFPSS was set up and financed by staff (1/3rd) and the Office (2/3rd) and has performed very well since its inception: it now has a value of over €8 billion.
However, in more recent years the Office has departed from this decision and instead injected only a fraction of the operating surplus into the RFPSS while retaining large parts of the money within the EPO treasury.
According to the IFRS2 accounting method, the EPO accounts show a negative equity of about €12 billion, mainly due to long term obligations such as pension obligations4. As should be apparent from the example in the footnote below, this negative equity is very sensitive to the discount rate applied to these obligations. The discount rate applied according to the
IFRS depends on the bond markets and is thus inherently volatile from one year to the next. For example, in 2011, this negative equity was €1.9 billion (applying a discount rate of 5.38%), which is less than the start-up capital for the EPOTIF. In 2014, it was calculated at some €12 billion (applying a discount rate of 1,61%),very similar to today’s figure. However, in 2015 some €4,5 billion of the negative equity “disappeared” without any substantive change in the operational income, simply due to applying the higher discount rate of 2,6%. Therefore, there would appear is no reason to now panic and take hasty or rushed decisions.
The President has followed a proposal in the second financial study to invest the present and future office treasury money to cover for these huge, fictive obligations in a new fund under new management. The more straight forward approach would have been to simply invest the money in the existing RFPSS.
However, on the proposal of the President, the Budget and Finance Committee (BFC) approved the setting-up of a new external EPO Treasury Investment Fund (EPOTIF)5.
The staff representation is strongly opposed to the creation of another fund, in particular one that is managed externally and whose investment strategy will lack the necessary internal checks & balances to avoid high risk investments, see sc17207cl, su18038cl and su18039cl (letters sent to AC and Auditors). At the last BFC meeting, the delegations also asked for more information: the German Delegation requested to review any contracts ahead of any decision on fund management. In 2017, the German Bundesrechnungshof gave a negative opinion on setting up such risky funds in 2017. Perhaps unsurprisingly, the President declined all requests to provide any detailed contract data to the BFC, the very body who are supposed to make informed decisions based on the financial situation of the EPO.
The RFPSS fund management provides already for the appropriate checks and balances and risk limiting mechanisms. Furthermore, the costs of the RFPSS management are only a third of those estimated for the new outsourced EPOTIF. Finally, the RFPSS has to date performed very well, producing higher returns on average than those predicted for the EPOTIF.
It is extraordinary that this far reaching proposal with no meaningful risk limits (the only one contained in the proposal is ill-defined and therefore does not cover a number of risks6) has not been put to the AC for vote, rather only to the BFC in 2017. As such, we believe that this decision was taken ultra-vires by the BFC. Further to the above obvious argument raised by the staff representation, a number of AC delegations stated back in 2017 that this important and far reaching decision should be deferred until the new President takes up office next month. However, the incumbent President stated that it would be only a further loss of time and money if the cash reserves (€2.4 billion) were not be invested as soon as possible. According to his estimates, the gain foreseen for the first year is estimated to €70 million and then €100 million per annum from the next year onwards.
Had the President, however, simply followed the AC decision in the early 1980’s (CA/27/83 point 19) to transfer any surplus into the RFPSS, then the EPO would have already accumulated gains in the order of several hundred million Euros over the past years and the money would have been safely placed in low-risk investments. SUEPO strongly opposes such risky institutionalized gambling with the staff's and the applicant's money. If it all goes wrong, who will foot the bill?
SUEPO have informed the Auditors on the situation and asked them for their opinion.
SUEPO will urgently address this issue with the new President Mr. Campinos: a swift return to a more meaningful and safe financing of our own social security. Meanwhile, all legal means will be explored to minimise the impact of the new fund on the Office’s finances and any appropriate action will be taken.
SUEPO fights for your rights.
Your SUEPO Central
_____ 1 EPO staff and the applicants 2 BFC document CA/27/83 point 19 endorsed by the AC in June 1983 with CA/PV 16 pg 69, para 195ff 3 a method introduced for listed companies and which is not properly adapted for “business models” such as public services, particularly for those of patent offices like the EPO 4 The vast majority of the EPO’s long term obligations are pension obligations whose present value strongly depends on the discount rate applied. For illustration, to pay someone €1000 pension in 50 years’ time, you would have to put aside today either €68,77 [1000/(1+5.5%)50] if you apply a discount rate of 5,5% or €475 [1000/(1+1.5%)50] with a discount rate of 1,5%,a difference of €406. The actuaries who make a recommendation for the EPO’s pension contributions use the same calculation method as IFRS for this calculation, but apply a discount rate of 5.5%. Since the IFRS discount rate is currently much lower than that, the apparent long term pension obligations calculated according to the IFRS method are much higher, thereby suggesting that the EPO should have put much more money aside to cover these pension obligations than it actually did. This over-valued obligation directly inflates the negative equity. Consequently, it is this perceived underfunding that contributes the lion share to the negative equity. This would change drastically through raising discount rates and rates do change considerably with time. For example, in the first years of this century, with higher discount rates, the equity gap was rather small. If the discount rate were to increase to figures like we enjoyed in the 1980’s, then any lingering negative equity due to pension obligations could be transformed into a high surplus. 5 The German delegation voted against as the Bundesrechnunghof had not provided its consensus; three delegations abstained (IT, IE, CZ); two delegations (PT, LI) were absent. All others voted in favour. 6 There, actually, isn‘t a single risk measure which can cover all the aspects of financial risks arising from different assets. This is why the RFPSS and similar funds use a combination of different risk measures.